Seed IQ™ Quantum Financial Compute
Financial pricing and risk
that does not sample
Seed IQ™ changes financial risk from a sampling problem into a computation problem.
Using governed fault-tolerant quantum compute for direct financial pricing and risk modeling, Seed IQ™ Intelligence + Quantum replaces massive statistical sampling with deterministic, repeatable results.
Machine precision
20,000 options validated against QuantLib
35x throughput
vs. the published NVIDIA 8xH100 STAC-A2
Zero run-to-run spread
Identical inputs, identical result
25 API operations
Across pricing, portfolio risk, and desk analytics
Compute the risk. Not a sample of it.
The Shift
For complex financial workloads, computing the answer directly has historically been beyond the practical reach of classical systems. The workaround has been massive statistical sampling across large CPU/GPU infrastructure, consuming substantial compute and energy to approximate the result.
Seed IQ™ changes that equation, directly computing deterministic, repeatable results with the speed required for increasingly real-time financial decision-making.
What it Computes
01
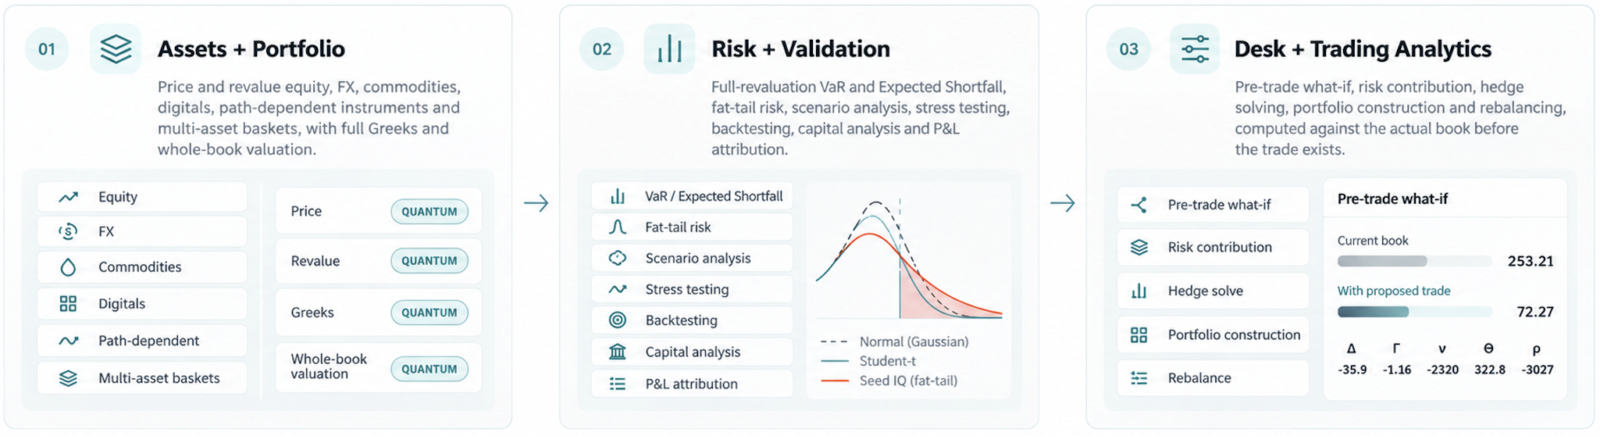
Pricing + Sensitivities
Instrument valuation, full Greeks, portfolio repricing and scenario pricing across increasingly complex financial instruments.
02
Market Risk + Scenario Compute
VaR, Expected Shortfall, stress testing, scenario analysis and P&L attribution through full portfolio revaluation.
03
Full-Book Risk + Stress
Full-revaluation VaR and Expected Shortfall, fat-tail analysis, named stress scenarios, backtesting and risk contribution across the book.
04
Portfolio + Capitial Compute
Portfolio analysis, capital allocation, risk budgeting, rebalancing and constrained optimization.
Built for institutional validation: backtesting, P&L attribution, model comparison and regulatory risk measures can be computed alongside the underlying pricing and portfolio risk.
The Full Workflow
A single, governed compute layer that spans pricing, risk, and trading analytics — computed directly on your instruments, your book, and your scenarios.
Commercial Value
Financial institutions often process enormous pricing and risk workloads across large books of positions, scenarios and sensitivities.
Seed IQ changes what institutions can compute, how often they can compute it, and how much infrastructure is required to get the answer.
01
Move risk into real time
Move beyond overnight batch cycles toward intraday and near-real-time computation.
02
See the tail the model misses
Compute VaR and Expected Shortfall against fat-tail scenarios rather than assuming normal-market behavior.
03
Eliminate sampling variance
Same inputs produce the same deterministic result, every time.
04
Trace the P&L
Trace how positions and scenarios drive portfolio value and risk.
05
Replace massive sampling infrastructure
Direct computation reduces reliance on large CPU/GPU clusters and energy-intensive simulation.
06
Integrate without rebuilding
Bring Seed IQ compute into existing institutional systems through API, rather than forcing a separate workflow.
Published benchmark
35× the throughput of NVIDIA's audited 8×H100 benchmark.
On AIX’s published quantum financial-compute benchmark, Seed IQ processed the benchmarked options-pricing workload producing deterministic results without Monte Carlo sampling.
Institutional Validation
01 - DEFINE
Choose the workload
Select a pricing, risk, portfolio or related computation already understood by the institution.
02 - BASELINE
Establish current results
Agree on inputs, incumbent outputs, current latency and success criteria.
03 - COMPARE
Run the computation
Compare precision, throughput, repeatability, scalability and compute requirements.
01 - DEPLOY
Move into production
Validated workloads can then be integrated through the Seed IQ Financial Compute API.
Built for Integration
Bring Seed IQ into your existing financial stack
The Seed IQ Quantum Financial Compute API is designed to integrate with institutional financial infrastructure across instrument-level and portfolio-level pricing, sensitivities, scenario analysis, and risk workflows.
Bring us a workload you already know.
We’ll benchmark Seed IQ Intelligence + Quantum directly against the system you use today.
© 2026 AIX Global, inc. – All rights reserved
Seed IQ™ Intelligence + Quantum
Legal Counsel: Gunderson Dettmer